Navigating the world of health insurance can often feel overwhelming, especially when trying to understand the intricacies of coverage and associated costs. One crucial aspect of your health plan is the Out-of-Pocket Maximum, which sets a limit on what you’ll pay for essential medical services in a given year. However, it’s important to note that this limit does not cover all expenses, leaving individuals and families to face several out-of-pocket costs. By gaining clarity on the specifics of what your Out-of-Pocket Maximum entails—and what it excludes—you can make better-informed decisions about your healthcare. In this post, we will explore eight significant health insurance costs that fall outside this maximum limit, providing you with the insight needed to budget effectively and avoid unexpected surprises.
Key Points
- The Out-of-Pocket Maximum does not include premium payments.
- Costs for non-covered services are excluded from the maximum.
- Out-of-network provider fees are typically not included.
- Cost-sharing elements such as copayments might not count.
- Certain prescription drug costs may not apply to the maximum.
- Expenses related to alternative therapies are often not covered.
- Deductibles may still apply even after reaching the maximum.
- Charges for services received abroad usually fall outside the coverage.
Related content:
How Much Does Crop Insurance Cost Per Acre?
Understanding Your Out-of-Pocket Maximum: What It Covers and What It Doesn’t
The Out-of-Pocket Maximum serves as a crucial financial shield in your healthcare journey, yet its specifics can often appear a bit nebulous. Essentially, this limit represents the most you’ll pay in a policy year for covered services. Once you hit this cap, your health plan usually covers 100% of your remaining medical expenses. However, it’s vital to note that not all expenses count towards this limit.
For instance, the following typically do count:
- Deductibles: The amount you pay before insurance starts to contribute.
- Co-pays: Fixed amounts you pay for doctor visits or prescription medications.
- Coinsurance: Your share of the costs after your deductible is met.
However, non-covered services, like elective procedures or out-of-network care, often don’t count towards the Out-of-Pocket Maximum. Therefore, it’s essential to carefully review your plan to fully understand its implications.
In my opinion, being informed about what your Out-of-Pocket Maximum entails can guide crucial decisions regarding your health expenses.
Common Misconceptions About Out-of-Pocket Maximums in Health Insurance
Despite the critical role of the Out-of-Pocket Maximum in health insurance, many people remain misinformed. One common misconception is that reaching this limit means all healthcare costs are covered. In reality, while it caps your personal expenses within a policy year, some costs—like premiums and certain out-of-network services—may not count toward this maximum. Consequently, individuals might still face unexpected bills. Furthermore, some believe the Out-of-Pocket Maximum applies to every family member individually, but it usually applies at the family level, offering collective protection. Therefore, if one member surpasses their individual cap, the family as a whole may benefit from additional coverage. It’s vital to read policy documents carefully and ask questions for clarity. Understanding these intricacies can significantly impact your financial planning concerning health care.
The Impact of Deductibles and Copayments on Your Out-of-Pocket Maximum
Understanding the nuances of deductibles and copayments is vital, as both significantly influence your financial responsibilities, particularly regarding your Out-of-Pocket Maximum. A deductible is the amount you pay before your insurance kicks in, and this initial cost can vary widely based on your plan. Consequently, if you have a higher deductible, it may take longer to reach your Out-of-Pocket Maximum, thus extending your period of higher costs.
On the other hand, copayments are fixed fees for specific services, which add another layer to your total expenses. Therefore, frequent visits to healthcare providers can quickly accumulate copays, potentially pushing you closer to that Out-of-Pocket Maximum. Ultimately, while understanding these terms may seem daunting, their interplay impacts how much you will spend throughout the year, making it essential to analyse your healthcare costs carefully.
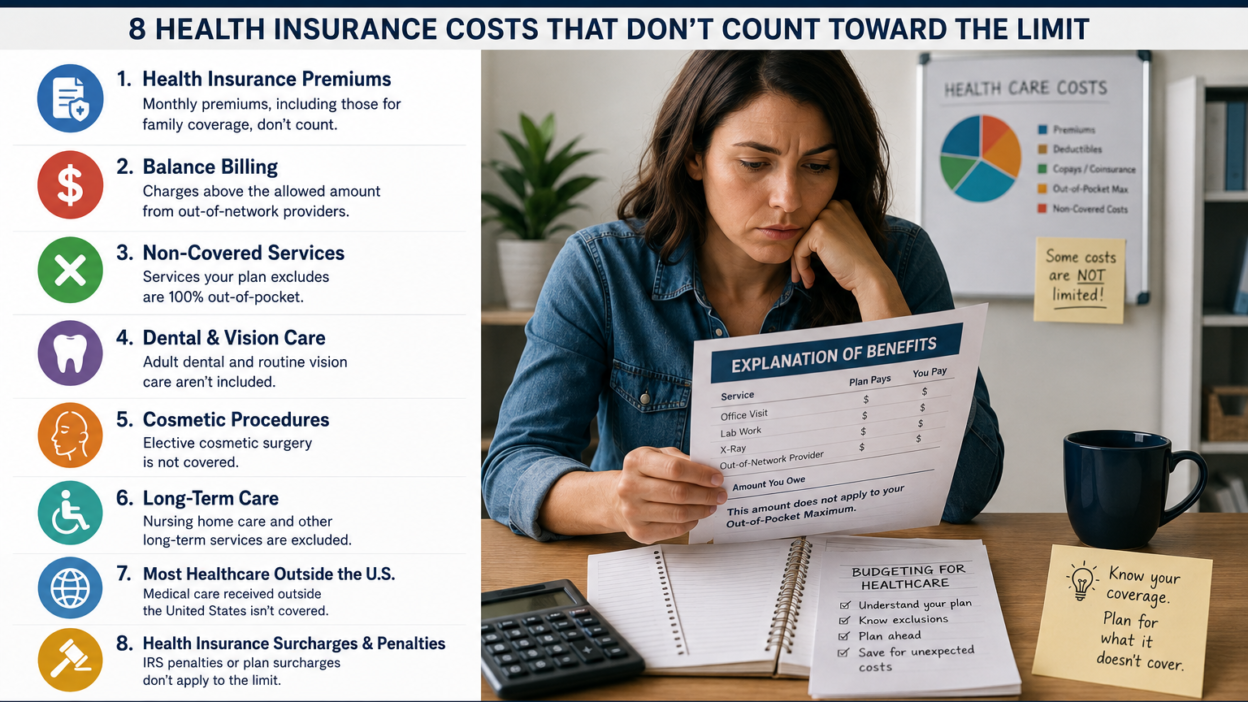
Exploring the Exclusions: 8 Key Health Expenses Not Counted Towards Your Maximum
Navigating the world of health expenses can be perplexing, particularly when it comes to understanding what counts towards your Out-of-Pocket Maximum. Regrettably, certain costs are often excluded, which may lead to unexpected financial obligations. Here are eight significant exclusions to consider:
- Premiums: Regular payments for coverage do not count.
- Non-covered Services: Treatments not included in your plan are excluded.
- Cosmetic Procedures: Often considered elective, these expenses are not counted.
- Out-of-Network Care: Costs incurred outside your insurer’s network may not apply.
- Over-the-Counter Medications: These purchases typically do not contribute.
- Alternative Treatments: Services like acupuncture are often excluded.
- Preventive Services: Certain screenings may have different rules.
- Penalty Fees: Any fines related to non-compliance with healthcare regulations don’t count.
Hence, it’s vital to review your health plan details to avoid surprises and ensure a comprehensive understanding of your Out-of-Pocket Maximum obligations.
Ultimately, keeping aware of these exclusions can significantly impact your financial planning.
Why Prescription Drugs May Fall Outside Your Out-of-Pocket Maximum
Prescription drugs can often lead to confusion regarding the Out-of-Pocket Maximum associated with your health insurance plan. While many medical services and treatments typically count towards this limit, certain medications may not. This exclusion can happen for various reasons, including whether the drug is classified as a specialty medication or if it is part of a tiered formulary that requires higher co-pays. Additionally, some plans might have specific rules governing how much of a drug’s cost contributes toward the Out-of-Pocket Maximum.
Furthermore, if you receive medications through a mail-order service or different pharmacies, it might affect your total out-of-pocket calculations. Therefore, it’s crucial to carefully examine your plan’s details. Ultimately, being informed can potentially save you from unexpected expenses, as not all prescriptions play a role in reaching the Out-of-Pocket Maximum.
Emergency Room Visits: Are They Part of Your Out-of-Pocket Expenses?
Emergency room visits can often lead to significant financial implications, potentially forming a crucial part of your out-of-pocket expenses. Many people may not realise how much they’ll need to pay after an unexpected hospital trip. Typically, your insurance will cover a portion of the costs, yet the responsibility can still fall heavily on individuals. Consequently, understanding your plan’s Out-of-Pocket Maximum helps in avoiding unforeseen expenses. However, factors such as copayments, deductibles, and the specific nature of care received can create ambiguity in total costs.
In many cases, individuals may hit their Out-of-Pocket Maximum with just a few emergency visits, particularly if additional treatments or tests are required. Therefore, it’s wise to be proactive about exploring your insurance coverage. After all, having clarity on these potential expenses may offer peace of mind when faced with a health crisis.
“In emergencies, knowledge about your healthcare plan can be as vital as the aid you receive.”
Empower yourself by keeping informed about how such scenarios impact your overall budget.
How Preventive Care Services Influence Your Out-of-Pocket Maximum
Understanding the relationship between preventive care services and your Out-of-Pocket Maximum can be quite beneficial. Preventive services, such as vaccinations and screenings, are often covered without a deductible, which means they can significantly help you manage costs. By utilizing these services, you may reduce the likelihood of more serious health issues, which could lead to higher expenses later on.
Moreover, many insurance plans have specific rules around how these preventive services affect your overall spending. Therefore, knowing which services are covered can allow you to better navigate your annual healthcare budget. To maximize your benefits, consider:
- Regular check-ups: Maintain your health proactively.
- Screenings: Detect potential issues early on, which can save costs.
- Vaccinations: Protect against preventable diseases, minimizing future medical expenses.
Ultimately, a proactive approach to preventive care can make a significant impact on your Out-of-Pocket Maximum, potentially easing financial burdens.
However, it’s crucial to review your specific plan details to fully understand what applies.
The Role of Network Providers in Maximizing Your Health Insurance Benefits
Network providers play a crucial role in helping you make the most of your health insurance benefits. By choosing a provider within your insurance network, you often access a wider range of services at reduced costs. This can significantly lower your out-of-pocket expenses, especially for preventive care. However, it’s essential to be aware that not all treatments or specialists might be covered, leading to potential surprises down the line.
Furthermore, ensuring that you stay informed about your plan’s details can prevent confusion. Understanding how your Out-of-Pocket Maximum works is vital; it caps your total expenditures in a given year. Nevertheless, if you opt for out-of-network services, you might find your Out-of-Pocket Maximum to be much higher, diminishing the advantages your insurance offers. Therefore, leveraging network providers is not just about cost savings but also about making strategic healthcare choices.
Ultimately, getting the most from your health insurance requires a blend of knowledge and proactive planning. The right network provider can act as a pivotal ally in navigating your benefits effectively.
Navigating Out-of-Pocket Costs: Tips for Reducing Your Financial Burden
Managing out-of-pocket costs can feel overwhelming, yet there are effective strategies to ease the financial strain. Start by reviewing your health insurance plan details, particularly the fine print regarding your Out-of-Pocket Maximum. Familiarising yourself with this limit can provide a clearer picture of potential expenses. Additionally, consider establishing a health savings account (HSA) to save tax-free funds for medical expenses. This can cushion the blow when unexpected costs arise.
Moreover, be proactive in discussing treatment options with your healthcare provider. In many cases, there might be alternatives that are equally effective yet more financially manageable. Therefore, always inquire about the estimated costs associated with your treatments. In my opinion, understanding these elements can greatly empower you. Ultimately, by applying these tips and keeping a close eye on your health finances, you may find it easier to stay within your Out-of-Pocket Maximum, thus reducing your overall financial burden.
Remember, while the complexity of medical expenses can be daunting, small, informed steps often lead to substantial savings. Additionally, tools like budgeting can help track and minimize those out-of-pocket costs over time.
When Your Out-of-Pocket Maximum Resets: What You Need to Know Each Year
The Out-of-Pocket Maximum is a crucial part of your health insurance plan, typically resetting at the beginning of each year. This reset can bring about uncertainty, particularly if you’ve budgeted for medical expenses. Understanding when and how this reset occurs is essential for effective financial planning.
Your Out-of-Pocket Maximum generally applies to costs like deductibles, copayments, and coinsurance, but its specifics can vary. Usually, all covered expenses contribute towards this limit, but some costs might not count, leading to confusion. Therefore, be sure to check your policy details annually.
Additionally, monitor your healthcare spending throughout the year, as reaching the cap means your insurance covers 100% of covered services thereafter. However, unexpected medical emergencies can lead to exceeding your limit quickly, so keep a close eye on your healthcare utilization.
| Key Points | Explanation |
|---|---|
| Annual Reset | This typically occurs at the start of each plan year. |
| Counting Costs | Not all expenses may count towards your Out-of-Pocket Maximum. |
| Utilization Awareness | Track your spend proactively to avoid surprises. |
You can also check these out.:
Out-of-pocket maximum/limit – Glossary
Conclusion
In navigating the complexities of healthcare costs, understanding your Out-of-Pocket Maximum can truly empower you. This limit serves as a safety net, ensuring that once you reach it, you won’t face additional expenses for covered services. Moreover, recognizing how this figure fits into your overall healthcare strategy can help alleviate financial stress. Therefore, staying informed and proactive about your insurance plan can lead to better decision-making and peace of mind. Ultimately, grasping these concepts allows you to approach your health care with confidence, knowing that you have a clear understanding of your financial boundaries.
Frequently Asked Questions
What is an out-of-pocket maximum?
An out-of-pocket maximum is the highest amount you will have to pay for covered healthcare services in a plan year. Once you reach this limit, your health insurance will pay 100% of covered services for the rest of the year.
How does the out-of-pocket maximum work?
The out-of-pocket maximum includes expenses like deductibles, copayments, and coinsurance. However, premium payments and non-covered services do not count towards this limit.
Is the out-of-pocket maximum the same for all insurance plans?
No, the out-of-pocket maximum can vary significantly between different health insurance plans. It’s important to review the specifics of your plan.
Does the out-of-pocket maximum reset every year?
Yes, the out-of-pocket maximum typically resets at the end of each plan year, meaning you will start paying out-of-pocket again at the beginning of a new plan year.
Are all medical expenses included in the out-of-pocket maximum?
Not all expenses are included. Expenses for non-covered services, premiums, and some other costs may not count towards the out-of-pocket maximum.
What happens if I reach my out-of-pocket maximum?
Once you reach your out-of-pocket maximum, your insurance company will cover 100% of the costs for covered healthcare services for the remainder of the plan year.
Can I have different out-of-pocket maximums for in-network and out-of-network services?
Yes, many health insurance plans have separate out-of-pocket maximums for in-network and out-of-network services, meaning you could pay more if you use out-of-network providers.
How is the out-of-pocket maximum different from a deductible?
A deductible is the amount you pay for healthcare services before your insurance begins to pay, whereas the out-of-pocket maximum is the total limit you’ll pay in a plan year, including deductibles, copayments, and coinsurance.
Can my out-of-pocket maximum change during the plan year?
Your out-of-pocket maximum should not change during the plan year unless there are specific changes in your health plan or regulations, although annual limits may be adjusted with each new plan year.
How do I find my out-of-pocket maximum?
You can find your out-of-pocket maximum in your health insurance policy documents, benefit summary, or by contacting your insurance provider directly.